


Despite persistent macro headwinds, momentum continues in the secondary market and industry insiders have adjusted their expectations upward yet again.
In early 2026, investors surveyed for William Blair’s 2026 Secondary Market Report forecast $250 billion in global secondary volumes this year, continuing a multiyear surge. In a survey conducted by William Blair this summer, investors’ forecasts ticked up to $252 billion.
Global Secondary Market Volume (in Billions)
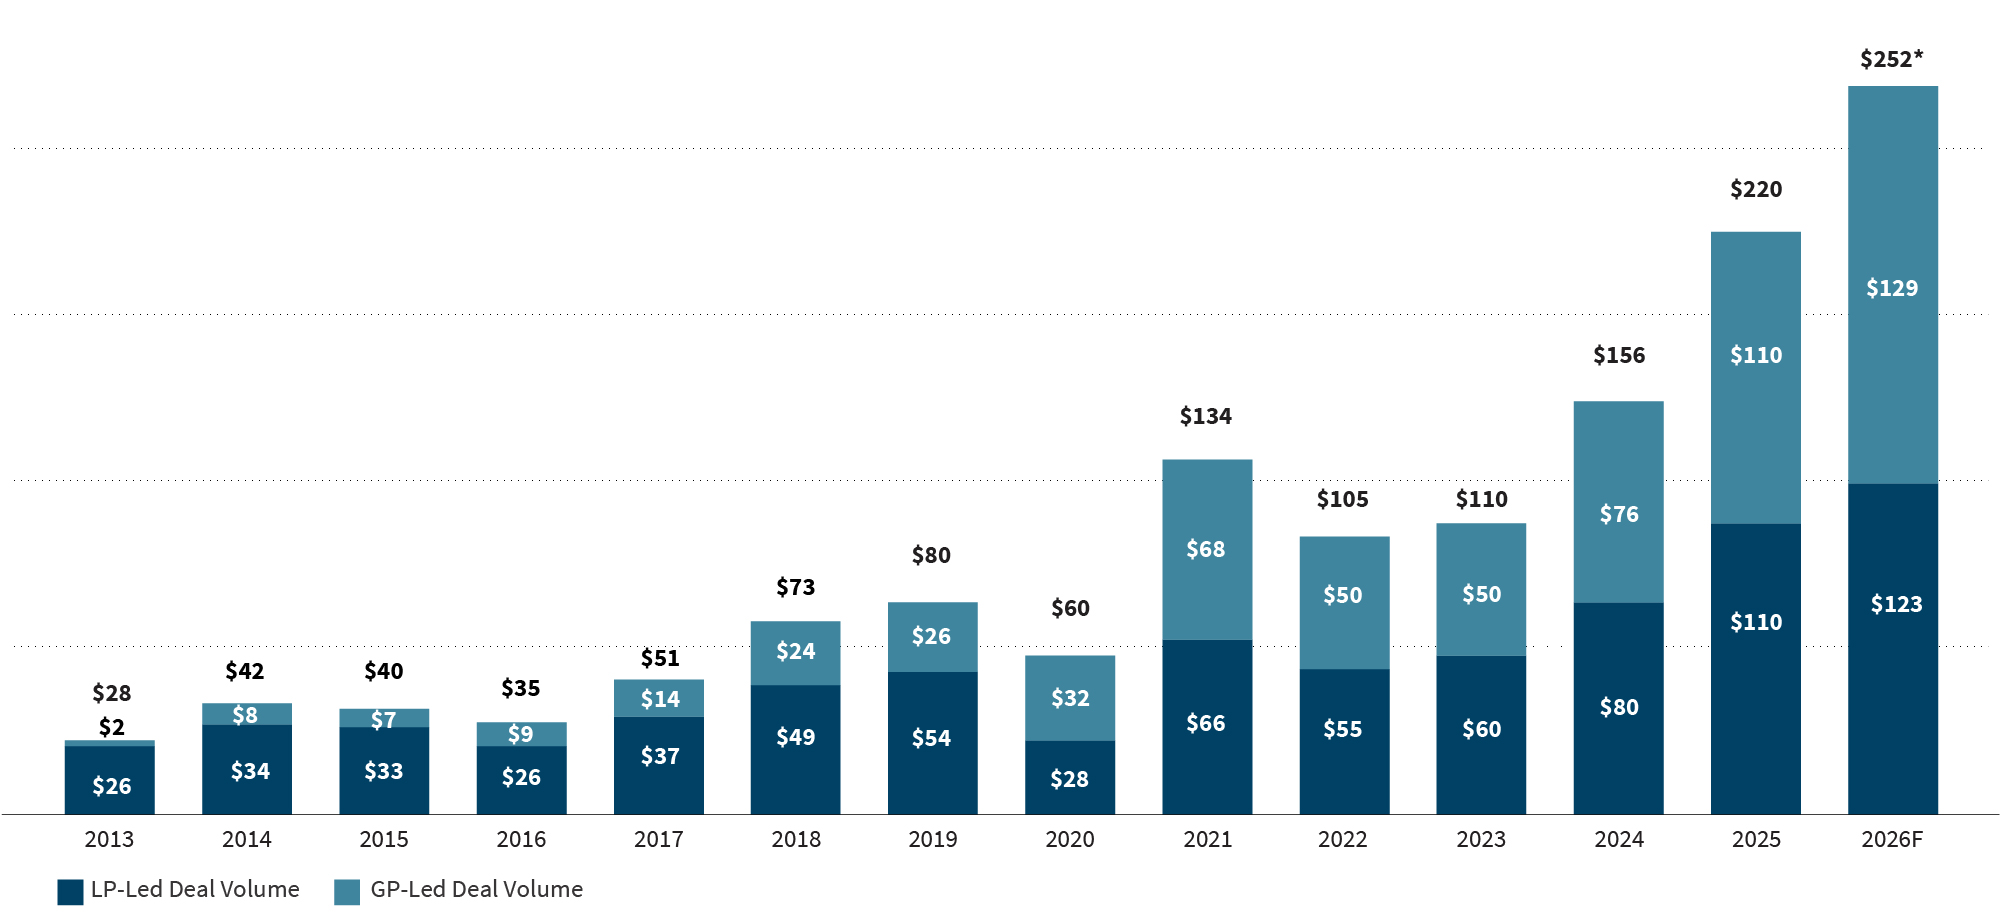
That trajectory aligns with the trend in recent years as trillions of dollars of unrealized value across private funds have been met with rapid capital formation among secondary investors. Indeed, despite a multiyear period of broader macroeconomic and geopolitical uncertainty, the secondary market has held steady and continued to grow.
Consistent with this observation, the vast majority of investors we surveyed in recent months said macroeconomic and geopolitical developments had not materially impacted their investment appetites. They also were more confident in the stability of pricing for both LP- and GP-leds than the investors we surveyed in summer 2025.1
This report examines the continued GP-led surge that is being fueled by investors’ appetite for continuation funds, re-engaged momentum in the LP-led market, and what to expect for the rest of 2026.
Stability for LP-Leds Amid AI Complications
Even amid the external headwinds, 94% of secondary investors surveyed by William Blair expect stable pricing for LP-leds.2 That sentiment occurs in a healthy market with marks that have come down since the spring, which bodes well for a potentially improved reference-date price optic. Buyers—especially those facing deployment pressure—are eager for additional supply and a new wave of scaled sales; many recent transactions have been of the tail-end or clean-up variety.
If history is any judge, the launch of one major deal could set others in motion in the LP-led market, which has been slower since the spring—though certainly not devoid of activity. While sentiment remains bullish and buyers are ready to pounce, there are caveats, the biggest related to ongoing AI disruption.
For portfolios lacking software and tech exposure, pricing has been quite healthy this year. But where software and tech represent a significant portion of a portfolio, transactions have been harder to execute. Some investors are passing on opportunities with significant software and tech exposure, or waiting things out. Others are trying to offer creative solutions. Overall, an eagerness to transact is leading to expectations of stable pricing—with reduced valuations perceived as baked into the new marks.
Another recent trend worth watching: large institutions (notably financial institutions and insurance companies) are growing more interested in structured alternatives—e.g., LP-led deals with GP-led characteristics or collateralized fund obligations—presenting competition for traditional LP-led solutions. That said, these alternatives are not the right fit for every investor.
Understanding Secondary Market Pricing
As of September 2026, LP-led sellers would be best characterized as slightly motivated, as pricing improved compared with the spring. As we predicted in our last newsletter, sellers became less fazed by macro events and marks improved.
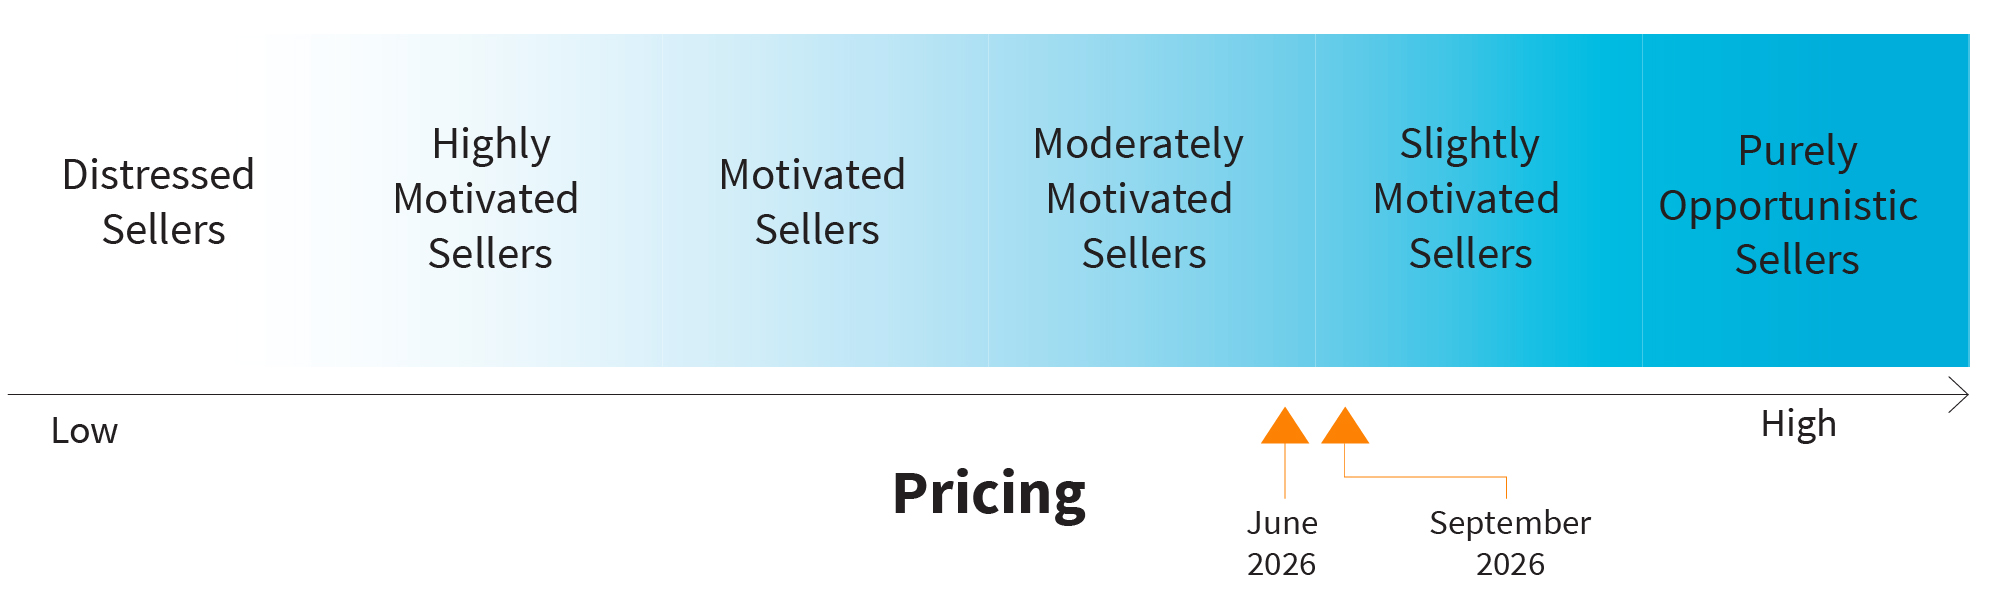
In particular, public pensions—sellers of some of the market’s largest deals—often have vendor-onboarding requirements that make regular-way sales the transaction of choice, with other structures replacing traditional counterparties with a relationship more akin to equity partners. The market’s acceptance of structures tailored to specific situations creates more optionality all around.
Single-Asset Category Drives GP-Leds
Similar to sentiment around LP-leds, 98% of investors we surveyed this summer brushed aside macro concerns and predicted the GP-led market would continue to support current valuation levels over the following six months.2
Secondary capital formation remains robust, with several new entrants raising large inaugural funds with incumbents also raising record amounts of capital. A subset of the new entrants includes large-cap private equity firms engaging in product extensions to participate in the GP-led market, helping to support capital-formation efforts. Additionally, existing fund of fund investors have been highly successful raising larger funds than previous vintages.
Continuation funds, as we have noted in previous reports, have become an alternative to M&A and IPOs as sponsors look to generate distributions to LPs—and single-asset continuation funds (“SACF”) have led the category’s remarkably quick growth over the past year. Behind the heightened SACF focus is increased capital formation from many of the previously mentioned private equity firms and large secondary investors raising strategies targeting concentrated GP-led transactions as well as a somewhat predictable pivot back to SACFs after strong activity in the multi-asset category during 2024 and early 2025.
The continuation fund market is still evolving, and smaller continuation fund transactions have been gaining momentum. While larger sponsors have embraced the structure, many lower-middle-market and middle-market firms remain first-time issuers. Simultaneously, growth in the number of investors that can write meaningful checks for lower-middle-market and middle-market assets has scaled, creating a significant opportunity for competitive tension. This backdrop has put forth a strong venue for middle-market sponsors to transact.
Looking Ahead
The final months of the year look promising for secondaries, despite persistent macro uncertainties. For LP-leds, the fourth quarter of 2026 might be a good time to launch a deal, which is not always the case. Buyers, given the trends noted above, are still working to meet their deployment targets, meaning launching a deal in the year’s final months could yield a good result.
GP-led activity continues to rise, and the second half of the year is expected to have more activity than the first. The single-asset tailwind will likely continue as more investors establish strategies to participate, those groups raise additional funds, and sponsors become repeat issuers of the product. The GP-led market is in a strong position as the fourth quarter begins.
William Blair’s Private Capital Advisory team would welcome the opportunity to share our perspectives and discuss how these market themes affect you. Contact us to learn more.
Transactions Spotlight
 William Blair acted as the exclusive financial advisor to Centauri Health Solutions (Centauri) and Abry Partners (Abry) in connection with the raising of a single-asset continuation fund to acquire Centauri from Abry Fund IX and the sale of Centauri’s Provider Solutions business.
The divestiture closed in January 2026, and the continuation fund closed in June 2026. The transactions were the latest examples of William Blair leveraging its fully integrated platform, combining extensive continuation fund expertise with world-class healthcare IT knowledge. The continuation fund was anchored by Neuberger Berman and Apollo S3 as co-lead investors, with additional commitments provided by Abry’s existing limited and general partners.
Additional details:
- William Blair’s Private Capital Advisory team worked closely with the firm’s Healthcare IT team, leveraging sector knowledge, a historical company relationship, and deep continuation fund advisory expertise.
- The transaction is a strong example of William Blair’s ability to tailor a transaction process and structure to address specific client needs.
- In this instance, William Blair advised on the strategic divestiture in tandem with the continuation fund transaction, providing greater visibility in due diligence, and streamlining execution and transaction timelines.
Other Notable Transactions
 William Blair served as the exclusive financial advisor to Capital A Investment Partners on both the raising of its single-asset continuation fund and the concurrent refinancing process of De Jong Zuurmond. This transaction highlights William Blair’s growing presence in the European GP-led secondaries market and the ability to secure premium outcomes for William Blair clients. William Blair’s fully integrated PCA and Industrials M&A teams crafted a bespoke equity story, positioning the transaction with sector-specific insights that supported investors and lenders in their diligence.
 William Blair acted as exclusive financial advisor to Broadtree Partners, LLC, in connection with its successful closing of a multi-asset continuation fund with approximately $240 million of total commitments. William Blair also arranged a fund financing facility for Broadtree and the continuation fund in connection with the transaction closing. The transaction provided shareholder liquidity and committed follow-on equity for growth investments in four existing, high-performing Broadtree portfolio companies.
Disclosure
“William Blair” is a trade name for William Blair & Company, L.L.C., William Blair Investment Management, LLC and William Blair International, Ltd. William Blair & Company, L.L.C. and William Blair Investment Management, LLC are each a Delaware company and regulated by the Securities and Exchange Commission. William Blair & Company, L.L.C. is also regulated by The Financial Industry Regulatory Authority and other principal exchanges. William Blair International, Ltd is authorized and regulated by the Financial Conduct Authority (“FCA”) in the United Kingdom. William Blair only offers products and services where it is permitted to do so. Some of these products and services are only offered to persons or institutions situated in the United States and are not offered to persons or institutions outside the United States. This material has been approved for distribution in the United Kingdom by William Blair International, Ltd. Regulated by the Financial Conduct Authority (FCA), and is directed only at, and is only made available to, persons falling within COB 3.5 and 3.6 of the FCA Handbook (being “Eligible Counterparties” and Professional Clients). This Document is not to be distributed or passed on at any “Retail Clients.” No persons other than persons to whom this document is directed should rely on it or its contents or use it as the basis to make an investment decision.
- Source: William Blair Private Capital Advisory: 2026 Secondary Market Report and updated projections from a summer 2026 survey of 61 market insiders.
- Source: A summer 2026 survey of 61 market insiders conducted by William Blair.